Choosing a credit card can be difficult because there are many different options available. Some cards focus on cashback, while others offer travel rewards, introductory APR offers, flexible points, or premium benefits.
A credit card that works well for one person may not be suitable for another. Your spending habits, payment behavior, credit profile, and financial goals all matter when comparing cards.
Before submitting an application, it is useful to compare the important details side by side. This can help you understand the potential costs and benefits of each card.
Start With Your Financial Goals
Before comparing individual cards, decide why you want a credit card.
You may be looking for:
- Everyday cashback
- Travel rewards
- A card with a low APR
- A balance transfer option
- A card for building credit
- Flexible points
- A card without an annual fee
- Specific shopping or travel benefits
Your goal should determine which features deserve the most attention.
For example, someone who pays their balance in full every month may focus more on rewards and fees. Someone who expects to carry a balance may pay closer attention to the APR.
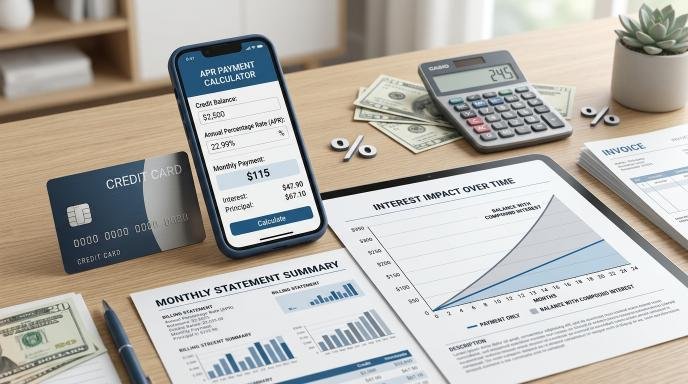
Compare APR
APR, or Annual Percentage Rate, represents the annualized interest rate associated with borrowing on a credit card.
If you regularly carry a balance, APR can have a significant effect on your overall costs.
When comparing cards, check:
- Purchase APR
- Introductory APR
- Balance transfer APR
- Cash advance APR
- Variable or fixed rate
- APR after an introductory period
For example, suppose Card A has a 20% purchase APR while Card B has a 28% purchase APR. If you carry a balance, the difference may become important.
However, if you consistently pay your statement balance in full and qualify for a grace period, the purchase APR may be less important for eligible purchases.
Compare Annual Fees
Annual fees can range from $0 to several hundred dollars depending on the card.
A card with an annual fee is not automatically expensive. It may provide rewards or benefits that can offset the cost.
For example:
Annual rewards + benefits used − annual fee = potential net value
Suppose a card has a $95 annual fee and you estimate that you will receive $250 in rewards and useful benefits during the year.
Your simplified potential net value would be:
$250 − $95 = $155
This is only an example. Your actual value depends on your spending and the card's terms.
Compare Rewards
Rewards are one of the most common reasons people choose a credit card.
Common reward types include:
- Cashback
- Points
- Airline miles
- Hotel rewards
- Category bonuses
- Welcome bonuses
Do not compare reward percentages alone. Consider whether the reward structure matches your spending.
For example, a card offering high rewards on dining may not be particularly useful if you rarely eat at restaurants.
A simple rewards comparison can look like this:
| Spending Category | Card A | Card B | Card C |
|---|---|---|---|
| Groceries | 2% | 3% | 1% |
| Dining | 1% | 3% | 4% |
| Travel | 1% | 2% | 5% |
| Other Purchases | 2% | 1% | 1% |
| Annual Fee | $0 | $95 | $150 |
The figures above are examples only. Actual reward rates and conditions vary by card.
Check the Welcome Bonus
Many credit cards offer a welcome bonus to new cardholders who meet certain spending requirements during a specified period.
A bonus can add significant value, but you should not spend beyond your normal budget just to qualify.
Before applying, check:
- Required spending amount
- Qualification period
- Bonus value
- Eligible transactions
- Eligibility restrictions
- When the bonus is credited
If the spending requirement is much higher than your normal expenses, the bonus may not be practical for you.
Review Foreign Transaction Fees
If you travel internationally or purchase goods from foreign merchants, check the card's foreign transaction fee.
Some cards charge a percentage on eligible foreign transactions, while other cards may not charge this fee.
For example, if a card charges 3% and you make $2,000 in eligible foreign transactions, the fee would be:
$2,000 × 3% = $60
This is only an illustration. Check the specific card's pricing information for the actual fee.
Compare Balance Transfer Terms
If you already have credit card debt, balance transfer terms may be important.
Some cards offer promotional APRs for eligible balance transfers.
However, a balance transfer may involve a fee.
When comparing balance transfer cards, look at:
- Promotional APR
- Length of promotional period
- Balance transfer fee
- Standard APR after promotion
- Credit limit
- Minimum payment requirements
Do not focus only on the introductory rate. Calculate the potential total cost of transferring the balance.
Look at Additional Benefits
Credit cards can offer benefits beyond rewards.
Depending on the card, these may include:
- Travel protections
- Rental car benefits
- Purchase protection
- Extended warranty features
- Airport lounge access
- Statement credits
- Fraud monitoring
- Hotel benefits
- Roadside assistance
The availability and terms of these benefits vary.
A benefit only has meaningful value if you are likely to use it. There is little reason to pay a large annual fee for travel benefits that you never use.
Check the Credit Limit
Your approved credit limit is determined by the card issuer based on its criteria.
A higher credit limit can provide more purchasing flexibility, but it does not mean you should spend more.
For example, if your credit limit is $5,000, you should still base your spending on your actual budget rather than treating the full limit as available income.
Your credit utilization can also be relevant to credit scoring models, so keeping balances manageable can be important for people focused on maintaining or improving their credit profile.
Review the Full Fee Structure
APR and annual fees are not the only costs to consider.
Before applying, look for:
| Fee | Why It Matters |
|---|---|
| Annual Fee | Recurring cost for keeping the account |
| Late Payment Fee | May apply when a required payment is late |
| Balance Transfer Fee | May apply when transferring eligible debt |
| Cash Advance Fee | May apply when obtaining cash |
| Foreign Transaction Fee | May apply to eligible foreign transactions |
| Returned Payment Fee | May apply when a payment is returned |
| Other Fees | May apply depending on the account and service |
Reading the card's current pricing and terms can help you identify costs that may not be obvious from advertisements.
Consider Your Payment Habits
Your payment behavior should influence your comparison.
If you always pay the statement balance in full, you may prioritize rewards, annual fees, and benefits.
If you regularly carry a balance, APR may deserve more attention.
If you are trying to build credit, payment history, manageable balances, and responsible account use may be more important than reward rates.
There is no single credit card feature that is most important for every consumer.
Create a Credit Card Comparison Table
Before applying, you can organize the information in a simple table:
| Feature | Card A | Card B | Card C |
|---|---|---|---|
| Purchase APR | Check terms | Check terms | Check terms |
| Annual Fee | Check terms | Check terms | Check terms |
| Cashback/Points | Check terms | Check terms | Check terms |
| Welcome Bonus | Check terms | Check terms | Check terms |
| Balance Transfer Fee | Check terms | Check terms | Check terms |
| Foreign Transaction Fee | Check terms | Check terms | Check terms |
| Travel Benefits | Check terms | Check terms | Check terms |
| Credit Requirement | Check issuer | Check issuer | Check issuer |
| Best Fit | Based on your needs | Based on your needs | Based on your needs |
Filling out this table using current information from each card issuer can make the comparison much easier.
Don't Apply Based Only on Advertisements
Credit card advertisements often highlight the most attractive features, such as cashback rates, welcome bonuses, or travel rewards.
However, the advertised benefit may have conditions, spending limits, or eligibility requirements.
Before applying, read the official pricing information and cardmember agreement.
Pay particular attention to introductory offers because promotional rates and bonuses generally have specific conditions and expiration periods.
Final Thoughts
Comparing credit cards before applying can help you understand both the potential benefits and costs of each option.
Start by identifying your financial goals and spending habits. Then compare APR, annual fees, rewards, welcome bonuses, balance transfer terms, foreign transaction fees, and additional benefits.
Do not choose a card simply because it offers the largest bonus or highest reward rate. A card should fit the way you actually manage your money.
Most importantly, review the current terms before applying because APRs, fees, rewards, promotional offers, and eligibility requirements can change.
A careful comparison can help you select a credit card based on your own financial needs rather than making a decision based only on advertising.